Expense management · 13 min read · Updated:
What is a gider pusulası (expense voucher) and how do you issue one? Withholding and returns
When you buy goods or services from someone who can't issue an invoice, the gider pusulası (expense voucher) is how you document the cost. You, the buyer, issue it, and in some cases the withholding tax is your responsibility too.
In short
- A gider pusulası is the document that first- and second-class merchants, self-employed professionals and book-keeping farmers issue for goods bought from, or work done by, people who aren't subject to tax (VUK Article 234).
- Unlike an invoice, it's issued by the buyer, not the seller; it's made out in two copies, signed by the seller, and one copy is given to them.
- On purchases from tax-exempt tradespeople, the buyer withholds income tax from the payment and declares it on the muhtasar (withholding) return by the 26th of the following month; the rate depends on the type of goods or service.
- When an end consumer returns goods, the return can be documented with a gider pusulası issued by the seller; on this voucher the VAT of the returned goods is shown separately.
- In Heyşirket, the Take a return window on a sales invoice prepares a gider pusulası PDF for returns; a gider pusulası for a purchase is recorded as an expense, and withholding isn't calculated automatically.
The village producer who brings firewood to your workshop, the day labourer who clears your warehouse, or someone who brings in scrap can't issue you an invoice. But the money you pay is a business expense, and it needs a document behind it. The gider pusulası (expense voucher) fills exactly that gap.
In this article we explain what a gider pusulası is, who issues it and when, what goes on it, and when withholding tax comes into play. Then we look at the voucher used for returns and where it sits in Heyşirket. For the bigger picture of which document supports which expense, see expense management and document order.
Part 1 · Definition What is a gider pusulası?
A gider pusulası is a document that you, as the buyer, issue when you buy goods from, or have work done by, someone who isn't subject to tax. It's governed by Article 234 of the Vergi Usul Kanunu (VUK, the Tax Procedure Law) and counts as a document that replaces an invoice.
The key difference from an invoice is who issues it. The seller issues an invoice. The buyer issues a gider pusulası, because the other party isn't a taxpayer with an obligation to issue documents.
| Invoice | Gider pusulası | |
|---|---|---|
| Who issues it? | The seller | The buyer (your business) |
| Who is the other party? | A taxpayer seller | A person not subject to tax, or a tax-exempt tradesperson |
| Signature | The seller's | The person who sold the goods or did the work |
| Copies | Electronic or paper | Two copies, one given to the seller |
| Withholding | Usually none | May apply depending on the seller |
Part 2 · Scope Who issues a gider pusulası, and when?
Under VUK 234, those who issue a gider pusulası are first- and second-class merchants, self-employed professionals and farmers who keep books. In other words, any company or sole trader keeping books on the balance-sheet or business-account basis can issue one.
The other party must not be subject to tax. Common cases are:
- Purchases from tax-exempt tradespeople: people who make things by hand at home, sell as street vendors or collect scrap and are exempt under Article 9 of the GVK (Income Tax Law).
- Work done by a non-taxpayer: someone without a tax registration who does a one-off repair, move or similar job.
- Second-hand goods from a private person: someone with no commercial activity who sells your business a used item.
- Returns from end consumers: when a customer brings back goods they bought, you as the seller can document the return with a gider pusulası (Part 6).
Part 3 · Issuing How do you issue a gider pusulası, and what goes on it?
The law lists the information a gider pusulası must contain. You can use a pre-printed voucher book or your own template; what matters is that the details below are complete.
Steps to issue a gider pusulası
Add the date and a sequence number
Write the date the voucher is issued. Keeping vouchers in numbered sequence makes it easy to spot a missing one at month end.
Write the seller's identity details
The name, surname and address of the person selling the goods or doing the work are mandatory. Adding their Turkish ID number (TCKN) prevents questions later.
Describe the work or goods
Clearly state the type of work, or the kind and quantity of goods bought. Avoid vague words like "sundries".
Show the price and any withholding
Write the amount paid. If withholding applies, show the gross amount, the tax withheld and the net amount paid to the seller on separate lines.
Have it signed and hand over a copy
The voucher is signed by the person who sold the goods or did the work. It's made out in two copies; one goes to the seller and you keep the other.
That's why paying through the bank rather than in cash helps twice: it records where the money went, and in some cases it removes the need to issue a separate voucher.
Part 4 · Withholding When is tax withheld on a gider pusulası?
Withholding (stopaj) on a gider pusulası is income tax that the buyer deducts from the payment to a non-taxpayer and pays to the tax office on the seller's behalf. Not every voucher involves withholding; it depends on who the seller is and the type of work.
- Tax-exempt tradespeople: under item 13 of GVK Article 94, tax is withheld when paying for work done by, or goods and services bought from, exempt tradespeople. The rate is set by Presidential decision according to the type of goods or service; for scrap purchases, for example, it's 2%.
- Work done by a non-taxpayer: depending on the nature of the payment, wage withholding or another type of deduction may apply. Whether the person works for you regularly is decisive here.
- One-off, non-commercial purchase of goods: buying a used item from a private person who has no tradesperson exemption and isn't in business doesn't always lead to withholding.
Tax withheld is declared and paid with the muhtasar ve prim hizmet beyannamesi (withholding and social security return) by the 26th of the month following the payment. In most businesses the accountant files it; your job is to show the gross, withholding and net amounts correctly on the voucher and pass the details on in time.
| Net amount agreed with the seller | 9.800,00 TL |
|---|---|
| Withholding rate (scrap purchase) | 2% |
| Gross amount = 9.800 ÷ (1 − 0,02) | 10.000,00 TL |
| Tax withheld = 10.000 × 0,02 | 200,00 TL |
| Gross price written on the voucher | 10.000,00 TL |
The figures are illustrative. If you agreed a net amount with the seller, you gross it up; if you agreed a gross amount, the withholding is deducted from it and the seller receives less. The amount booked as an expense is the gross price.
If you'd like to understand the difference between VAT withholding (tevkifat) and income tax withholding (stopaj), see tevkifat and stopaj.
Part 5 · VAT Does a gider pusulası show VAT?
A gider pusulası issued for a purchase doesn't include VAT, because the seller isn't a VAT taxpayer. So the price you pay doesn't give you any deductible VAT; the full amount on the voucher is booked as a cost or expense.
A gider pusulası issued for a return is the exception. The VAT you charged on the original sale for goods taken back from an end consumer is shown separately on the voucher, so the VAT you declared on the sale can be corrected by the return.
Part 6 · Returns How is a gider pusulası used for returns?
When a customer brings back a product they bought, a business buyer issues the return invoice. An end consumer can't issue an invoice, so the return is documented with a gider pusulası that you issue as the seller or, for online sales, with the return section of the e-Arşiv invoice. If the money was refunded to a card or through the bank, the receipt can also replace the gider pusulası.
- Product comes back — Check the items and quantity
- Gider pusulası — With the returner's name and address
- Signature — Two copies, one to the customer
- Refund — Cash, transfer or to the card
The type of return document depends on the buyer and the sales channel. We cover the full table, partial returns and the difference between cancelling and returning in return and cancellation invoices.
Part 7 · Product Does Heyşirket issue a gider pusulası?
Short answer: yes for returns, no for purchases. We want to say this plainly, because the two cases appear in different places on screen.
| Case | What Heyşirket offers | What you do |
|---|---|---|
| Return from an end consumer | On the sales invoice detail, İade al (Take a return) › Gider pusulası düzenle; a PDF is prepared | Print two copies and have the customer sign |
| Refund paid to the bank or card | The Para banka ya da kartla geri ödendi option; the bank receipt replaces the voucher | Keep the receipt |
| Purchase from an exempt tradesperson or private person | No gider pusulası document is produced | Issue the voucher on paper and enter it with Gider kaydı ekle as type Diğer (Other) |
| Withholding on purchases | Not calculated automatically | Note gross, withholding and net, and pass them to your accountant |
On the return side the window guides you. If the customer is an e-Fatura taxpayer, the option defaults to the customer's return invoice. For an end consumer, Gider pusulası düzenle is preselected; you fill in the returner's name and address and enter the quantities of the returned items. When you click Gider pusulasını oluştur, the return is offset against the invoice's remaining balance and taken off your sales and VAT.
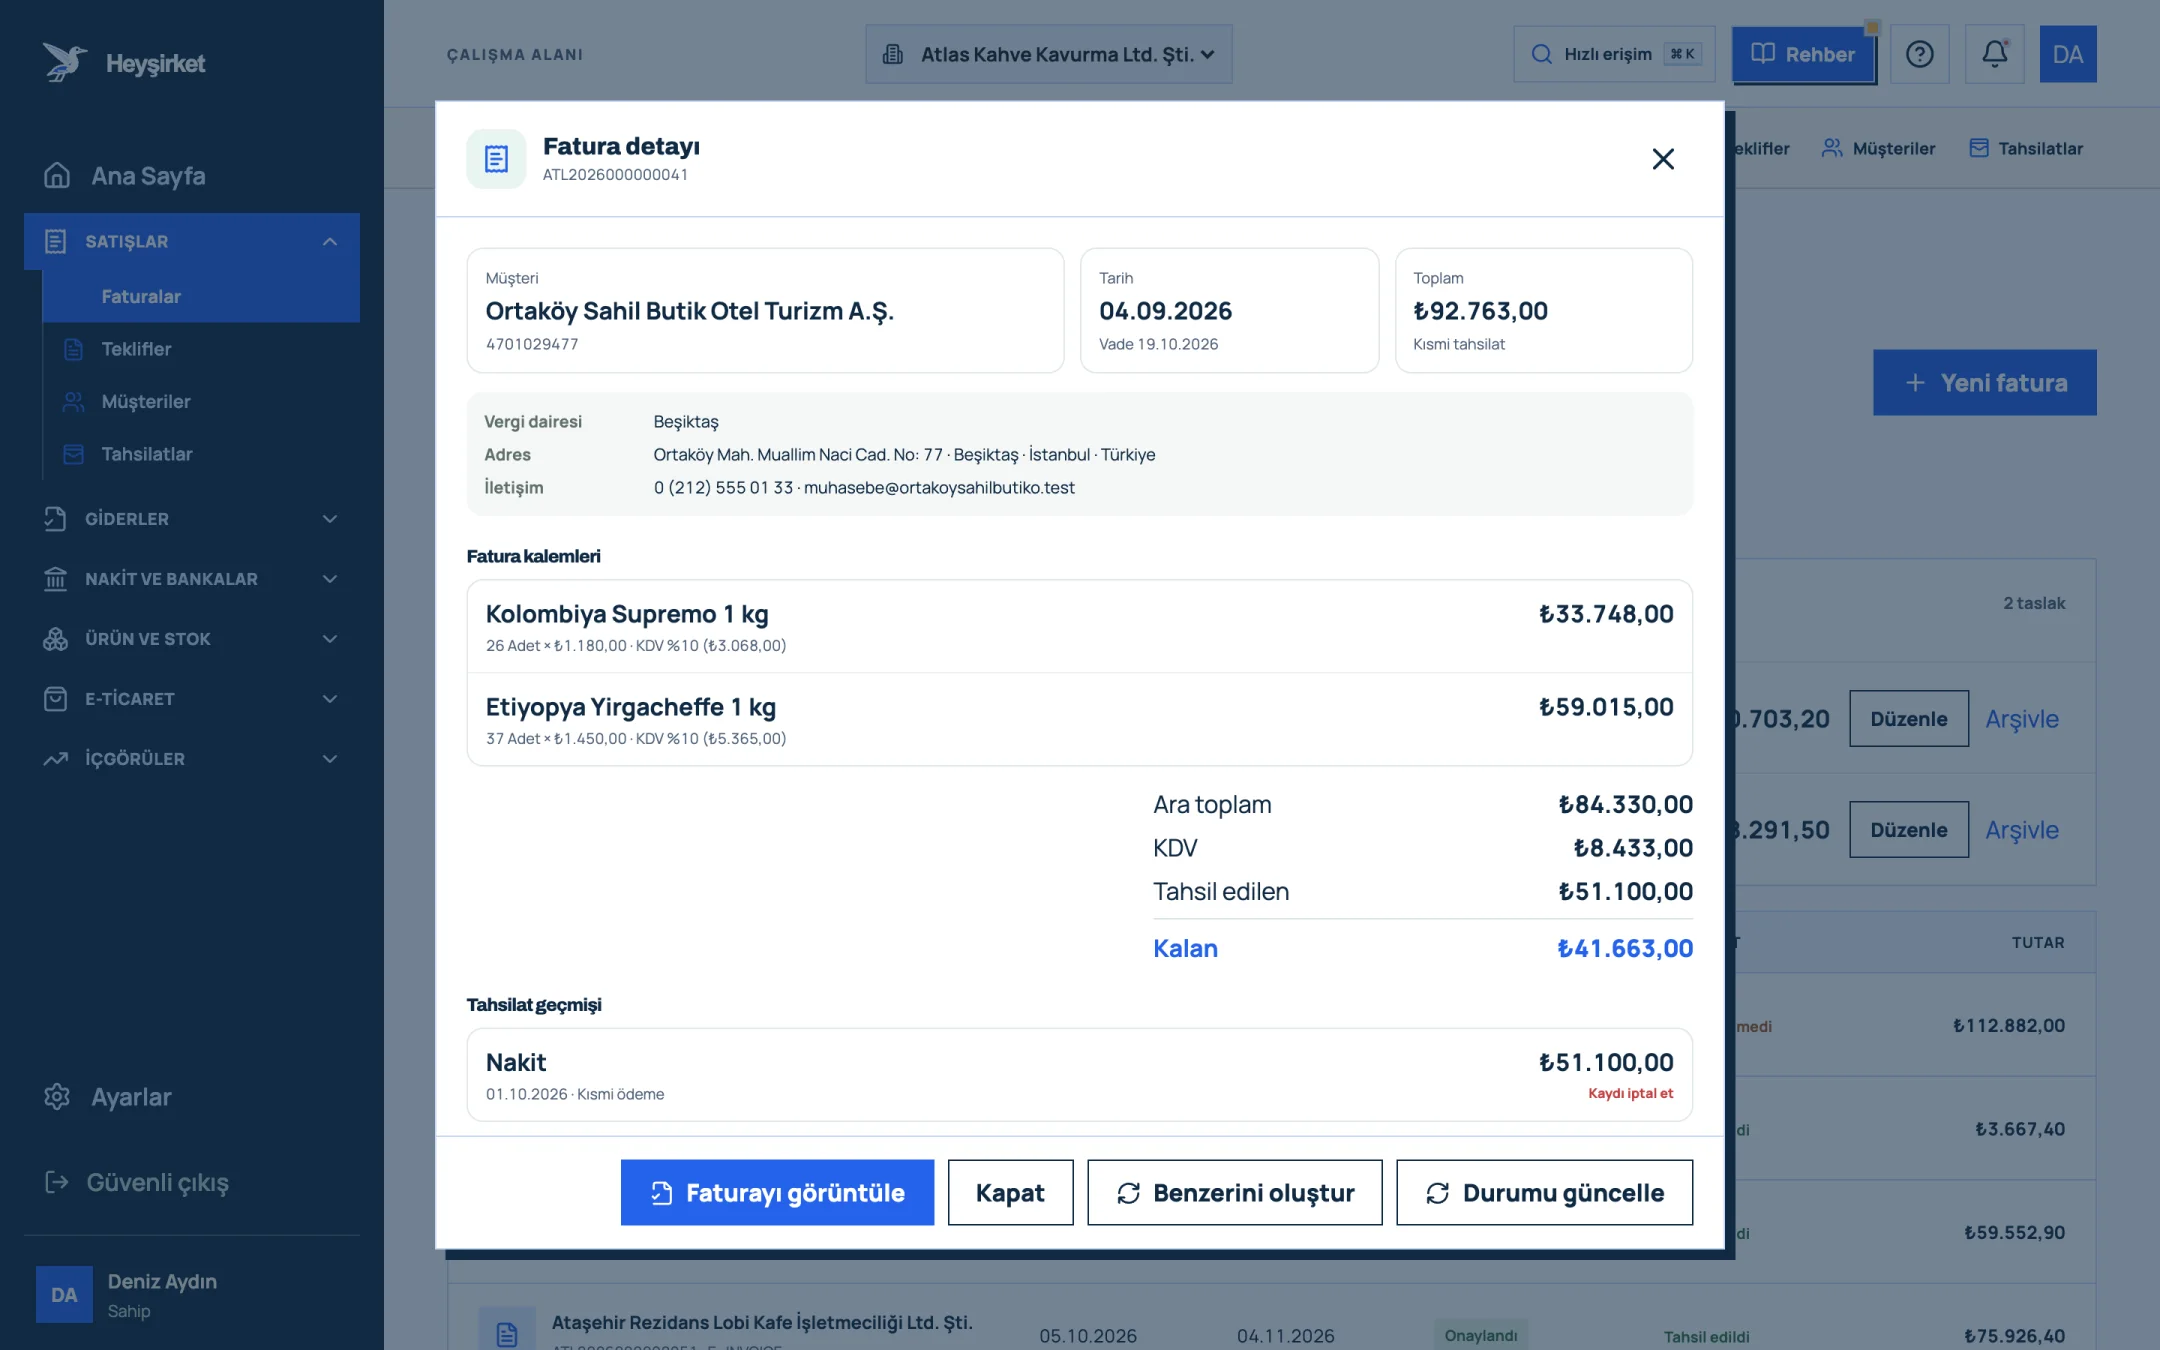
- 1. Invoice details window
- 2. View invoice / PDF
- 3. Collected and remaining amount
- 4. Collection history
- 5. Update status
On the purchase side, after issuing the paper voucher, open Gider kaydı ekle (Add expense), choose Diğer as the Belge türü (document type), enter the seller's name, their ID number in VKN / TCKN and the gross amount, and leave the VAT rate at zero. Writing the withholding amount in the Not field makes your accountant's month-end work easier. All the steps for entering an expense are in the how to enter an expense guide.
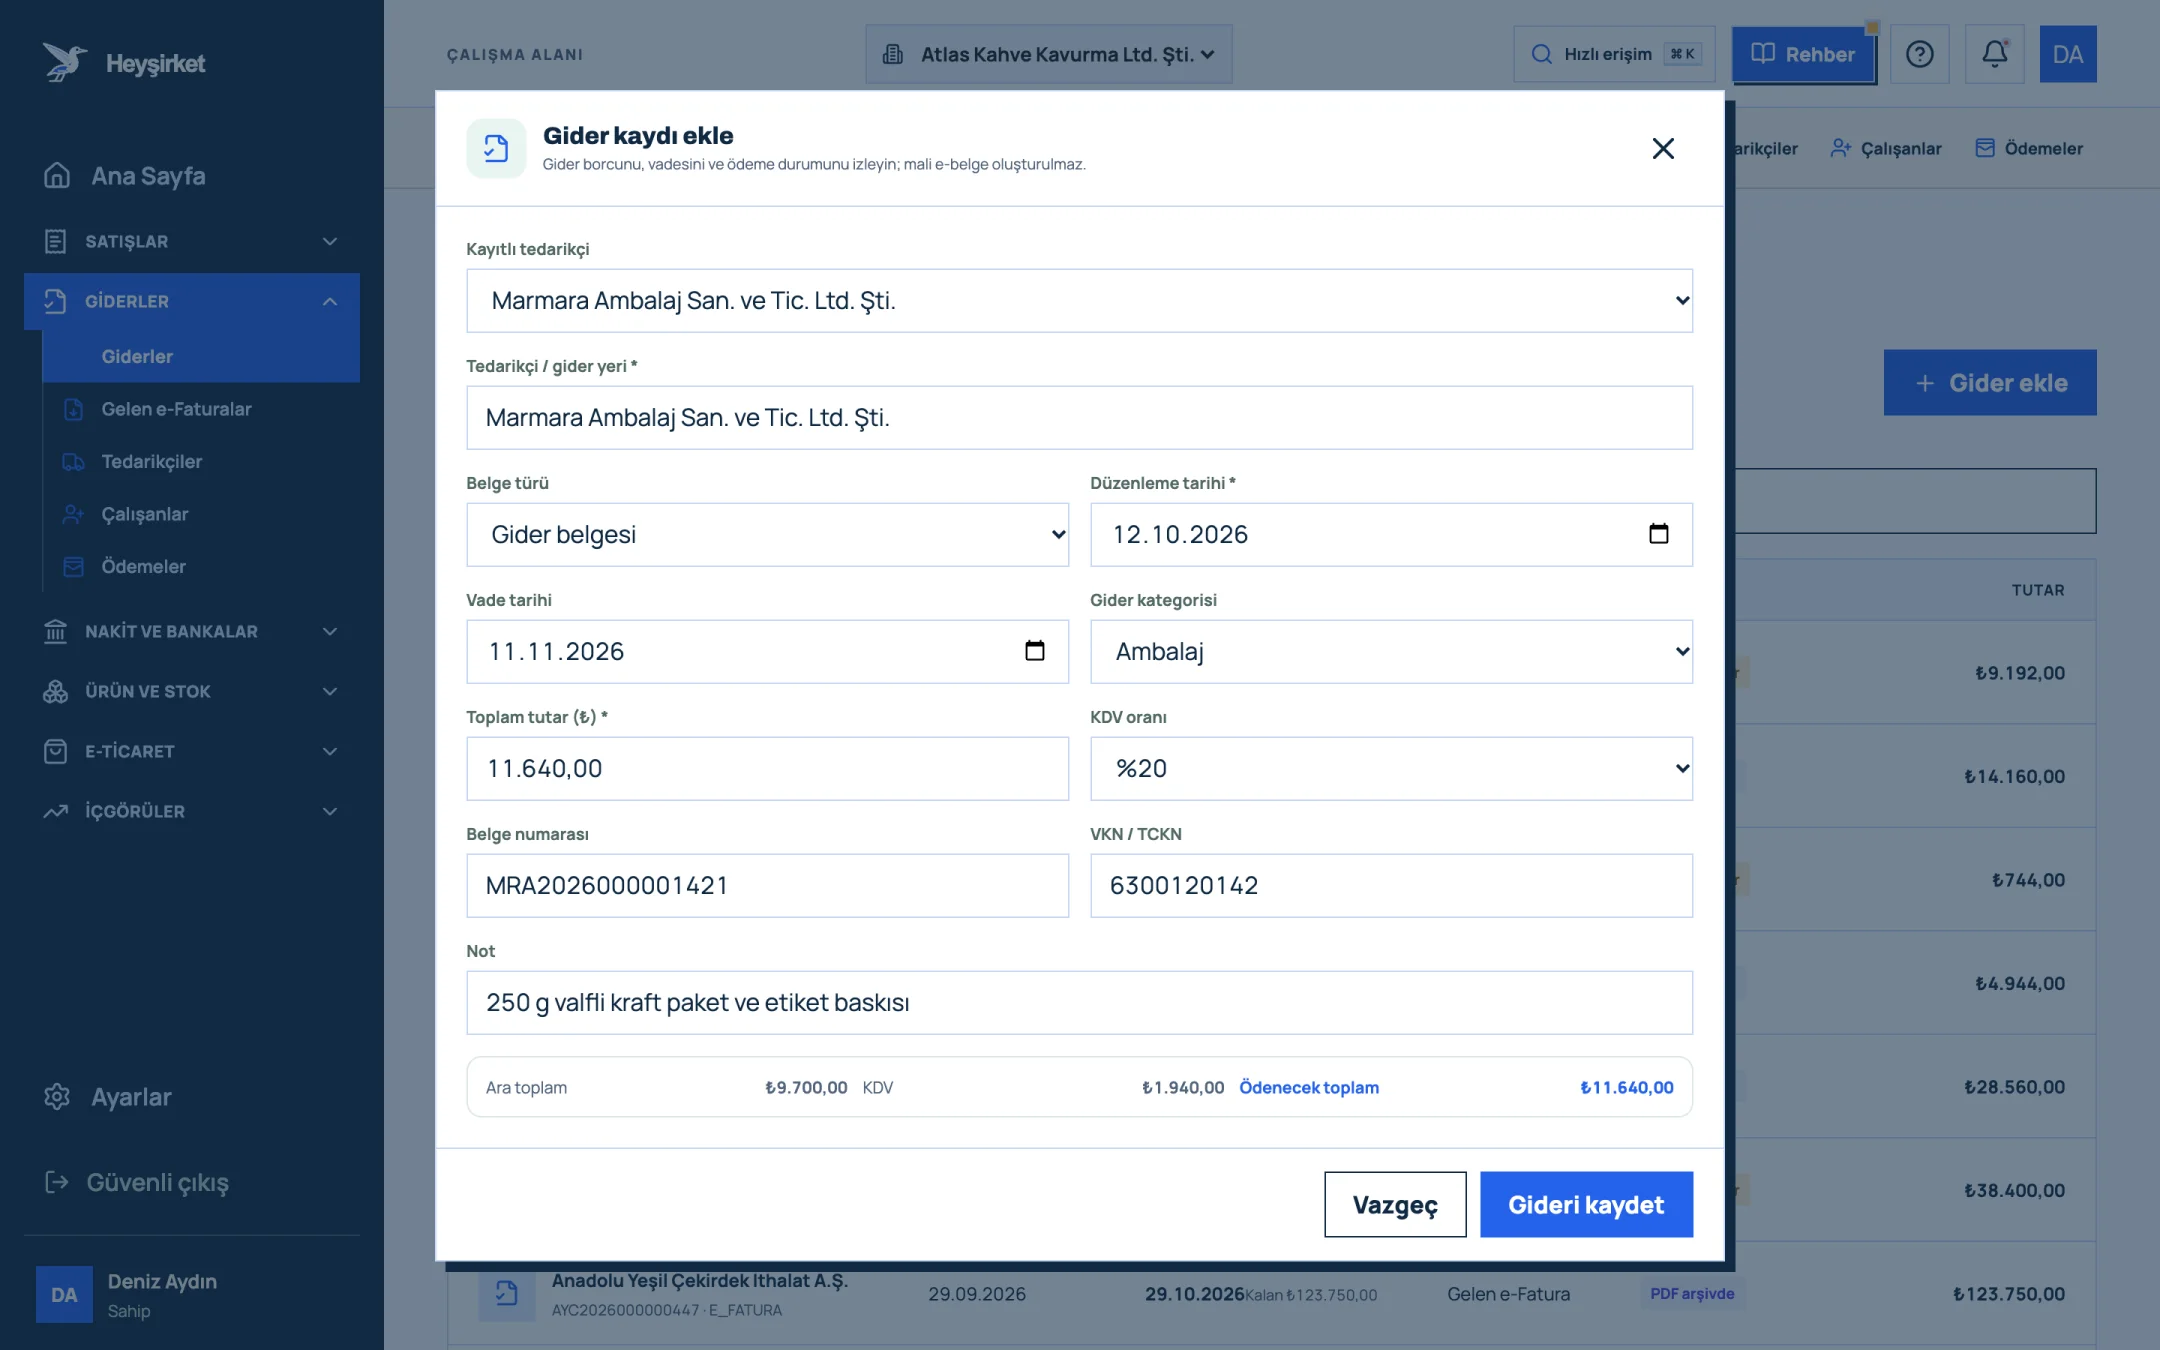
- 1. Supplier selection
- 2. Expense category
- 3. Amount and VAT rate
- 4. Subtotal, VAT and total payable
- 5. Save expense
Part 8 · Practice Gider pusulası checklist
Before you file the voucher
- I'm sure the other party genuinely can't issue an invoice.
- The seller's name, surname and address are written; I added their ID number too.
- The kind and quantity of goods, or the type of work, is clearly stated.
- If withholding applies, gross, withholding and net amounts are on separate lines.
- The seller signed the voucher and was given a copy.
- Where possible I paid through the bank and kept the receipt.
- I entered the expense in Heyşirket and passed the withholding on to my accountant.
Who issues a gider pusulası, the buyer or the seller?
The buyer. The business buying the goods or having the work done prepares the voucher, has the seller or worker sign it and gives them one copy. That's the most basic difference from an invoice.
Is tax withheld on every gider pusulası?
No. Withholding depends on the seller and the type of work. On purchases from tax-exempt tradespeople, tax is withheld under GVK Article 94; the rate varies by type of goods or service. A one-off purchase from a private person who isn't in business doesn't always involve withholding. Confirm your own case with your accountant.
When is the withholding on a gider pusulası declared?
It's declared on the withholding and social security return (muhtasar ve prim hizmet beyannamesi) by the 26th of the month following the payment and paid the same day.
Does a gider pusulası include VAT?
A gider pusulası issued for a purchase doesn't include VAT, because the seller isn't a VAT taxpayer. On a gider pusulası issued for a return from an end consumer, the VAT of the returned goods is shown separately.
Can a bank receipt replace a gider pusulası?
In the cases listed in VUK Article 234, receipts issued by a bank, payment institution or PTT are accepted in place of a gider pusulası. For example, if you refunded a return to the customer's account or card, the receipt may be enough. The receipt should show the seller's identity details and a description of the transaction.
Can I issue a gider pusulası in Heyşirket?
For returns from end consumers, yes: the Take a return window on a sales invoice prepares a PDF with the Gider pusulası düzenle option. For purchases from exempt tradespeople or private persons, Heyşirket doesn't produce a gider pusulası or calculate withholding; you issue the voucher on paper and record it as an expense.
Enter your vouchers as expenses After issuing the paper voucher, record it as an expense and send everything to your accountant from one list at month end. Go to expenses
Author: Heyşirket Editorial Team