e-Documents · 11 min read · Updated:
Invoice deadline and threshold in Türkiye 2026: the 7-day rule, 12,000 TL and penalties
When must you issue an invoice, below which amount is a retail receipt enough, and what happens if you're late? We've gathered the 2026 rules with the law articles and worked examples.
In short
- An invoice must be issued within at most 7 days of delivering the goods or performing the service; an invoice not issued in that time is treated as never issued (VUK 231/5).
- The 2026 invoicing threshold is 12,000 TL; it was set by VUK General Communiqué No. 588 and applies from 1 January 2026.
- The threshold applies to sales to buyers other than those listed in VUK 232, such as merchants and self-employed professionals; between those, an invoice is issued whatever the amount.
- Even if the price doesn't exceed 12,000 TL, an invoice must be issued if the buyer asks for one.
- Under VUK 353, failing to issue or obtain an invoice carries a special irregularity penalty of 10% of the amount, at least 17,000 TL for the first finding in 2026, rising with later findings.
The invoicing deadline and the invoicing threshold are the two rules small businesses skip most often. In a busy shipping week, invoices slip to month-end; at the till, “is a receipt enough?” stays unclear for small sales. Both answers are written plainly in the Tax Procedure Law (VUK).
In this article we cover the 7-day rule, the 2026 invoicing threshold, how the deadline is counted, and special cases such as partial deliveries, advances and ongoing services. At the end we show how the penalty for not invoicing is calculated, based on the official table.
Part 1 · Deadline How many days do you have to issue an invoice?
An invoice must be issued within at most 7 days of delivering the goods or performing the service. An invoice not issued within that time is treated by law as never issued. The rule is the same for paper invoices, e-Fatura and e-Arşiv invoices. We explain issuing an e-Fatura end to end in how to issue an e-Fatura.
The law also lets the Ministry of Treasury and Finance shorten this period for certain goods, services, sectors or taxpayer groups, or even require the invoice at the moment of delivery. So 7 days is a ceiling; a shorter period may apply to your business.
Part 2 · Counting How is the invoice deadline calculated?
The count starts from the date of delivery or service, not from the invoice. The delivery day itself isn't counted; the 7 days run from the next day. In practice, the day you get by adding 7 days to the delivery date is the last day you can issue the invoice.
| Delivery date | 3 October |
|---|---|
| Period counted | 7 days |
| Possible issue dates for the invoice | 3 – 10 October |
| Last day | 10 October |
A single invoice dated 31 October at month-end would miss the deadline for this delivery. Dates are examples.
What matters is the gap between the invoice's issue date and the delivery date. Preparing the invoice in time but sending it later, or backdating it after the deadline, both cause problems. With e-Documents the date and time are recorded in the system, so the gap is easy to see.
Part 3 · Threshold What is the 2026 invoicing threshold?
The 2026 invoicing threshold is 12,000 TL. The amount was set by VUK General Communiqué No. 588 and applies from 1 January 2026. In 2025 it was 9,900 TL. The threshold is updated every year in line with the revaluation rate and announced by the Ministry of Treasury and Finance.
Who the threshold applies to is often confused. Under VUK 232, merchants, self-employed professionals, simplified-method taxpayers, farmers keeping books and tax-exempt tradespeople must issue and obtain invoices for sales between them whatever the amount. The 12,000 TL threshold is for sales to other buyers, which mostly means final consumers.
| Buyer | Sale amount | Document |
|---|---|---|
| Merchant, self-employed professional, farmer, tradesperson (VUK 232/1) | Any amount | Invoice required |
| Final consumers and other buyers | Above 12,000 TL | Invoice required |
| Final consumers and other buyers | 12,000 TL or less, buyer asks | Invoice required |
| Final consumers and other buyers | 12,000 TL or less, buyer doesn't ask | A retail receipt or cash register (ÖKC) receipt may be used |
The invoicing threshold and the e-Arşiv threshold are different things. One answers “do I have to issue an invoice?”, the other “must the invoice I issue be electronic?”. From 2026, as a general rule, invoices are issued as e-Arşiv invoices whatever the amount; details for simplified-method and business-account taxpayers are in e-Fatura vs e-Arşiv.
Part 4 · Special cases When is the invoice issued in special cases?
The 7-day rule looks simple, but daily work raises questions. These are the most common:
- Partial deliveries: If goods go out in several shipments, each delivery starts its own 7-day period. You can combine several dispatch notes on one invoice, as long as the oldest one is still within its deadline.
- Shipping with a dispatch note: A dispatch note (irsaliye) doesn't replace the invoice. For goods shipped with a dispatch note, the invoice is still issued within 7 days of delivery and shows the dispatch note details.
- Advances and deposits: If an invoice is issued before the goods are delivered, the VAT chargeable event occurs when the invoice is issued, limited to the invoiced amount (VAT Law, Article 10). Decide with your mali müşavir (certified accountant) whether to invoice an advance.
- Ongoing or periodic services: For ongoing work such as consulting, maintenance or rent, the service date depends on the period in your contract. Agree with your mali müşavir which day to use, based on your contract.
- Returns: Different rules apply when sold goods come back; for returns from final consumers, documents such as an expense voucher (gider pusulası) come into play. Details in return and cancellation invoices.
Part 5 · Penalty What is the penalty for not issuing an invoice in 2026?
Not issuing an invoice, not obtaining one, or issuing one after 7 days so that it counts as never issued, triggers a special irregularity penalty under VUK 353. The penalty can apply not only to the seller but also to the buyer who didn't obtain the invoice.
The penalty is 10% of the amount, or the difference, that should have appeared on the document, but it can't fall below minimum amounts set by the number of findings. Since 2 August 2024, this minimum rises with each new finding at the same taxpayer.
| Finding | Minimum penalty (2026) |
|---|---|
| 1st finding | 17,000 TL |
| 2nd finding | 35,000 TL |
| 3rd finding | 53,000 TL |
| 4th finding | 70,000 TL |
| 5th finding | 87,000 TL |
| 6th and later findings | 170,000 TL |
| Annual cap per document type | 17,000,000 TL |
| Amount that should have been invoiced | 50,000 TL |
|---|---|
| 10% of the amount | 5,000 TL |
| 2026 minimum for the first finding | 17,000 TL |
| Special irregularity penalty applied | 17,000 TL |
Because the percentage is below the minimum, the minimum applies. Amounts are examples; in a real case other consequences such as tax loss penalties may also arise.
There is also a separate penalty when people not listed in VUK 232, usually consumers, fail to obtain an invoice they should have obtained. In 2026 it is 8,700 TL per document, with a total of 87,000 TL per calendar year.
Part 6 · In practice Not missing the deadline in Heyşirket
The easiest way not to miss the deadline is to link delivery and invoice. In Heyşirket accounting you keep outgoing dispatch notes on the Outgoing dispatch notes screen. A draft note doesn't change stock, the Dispatch confirmation records the outflow, and from a dispatched note you move to the invoice with Create invoice draft.
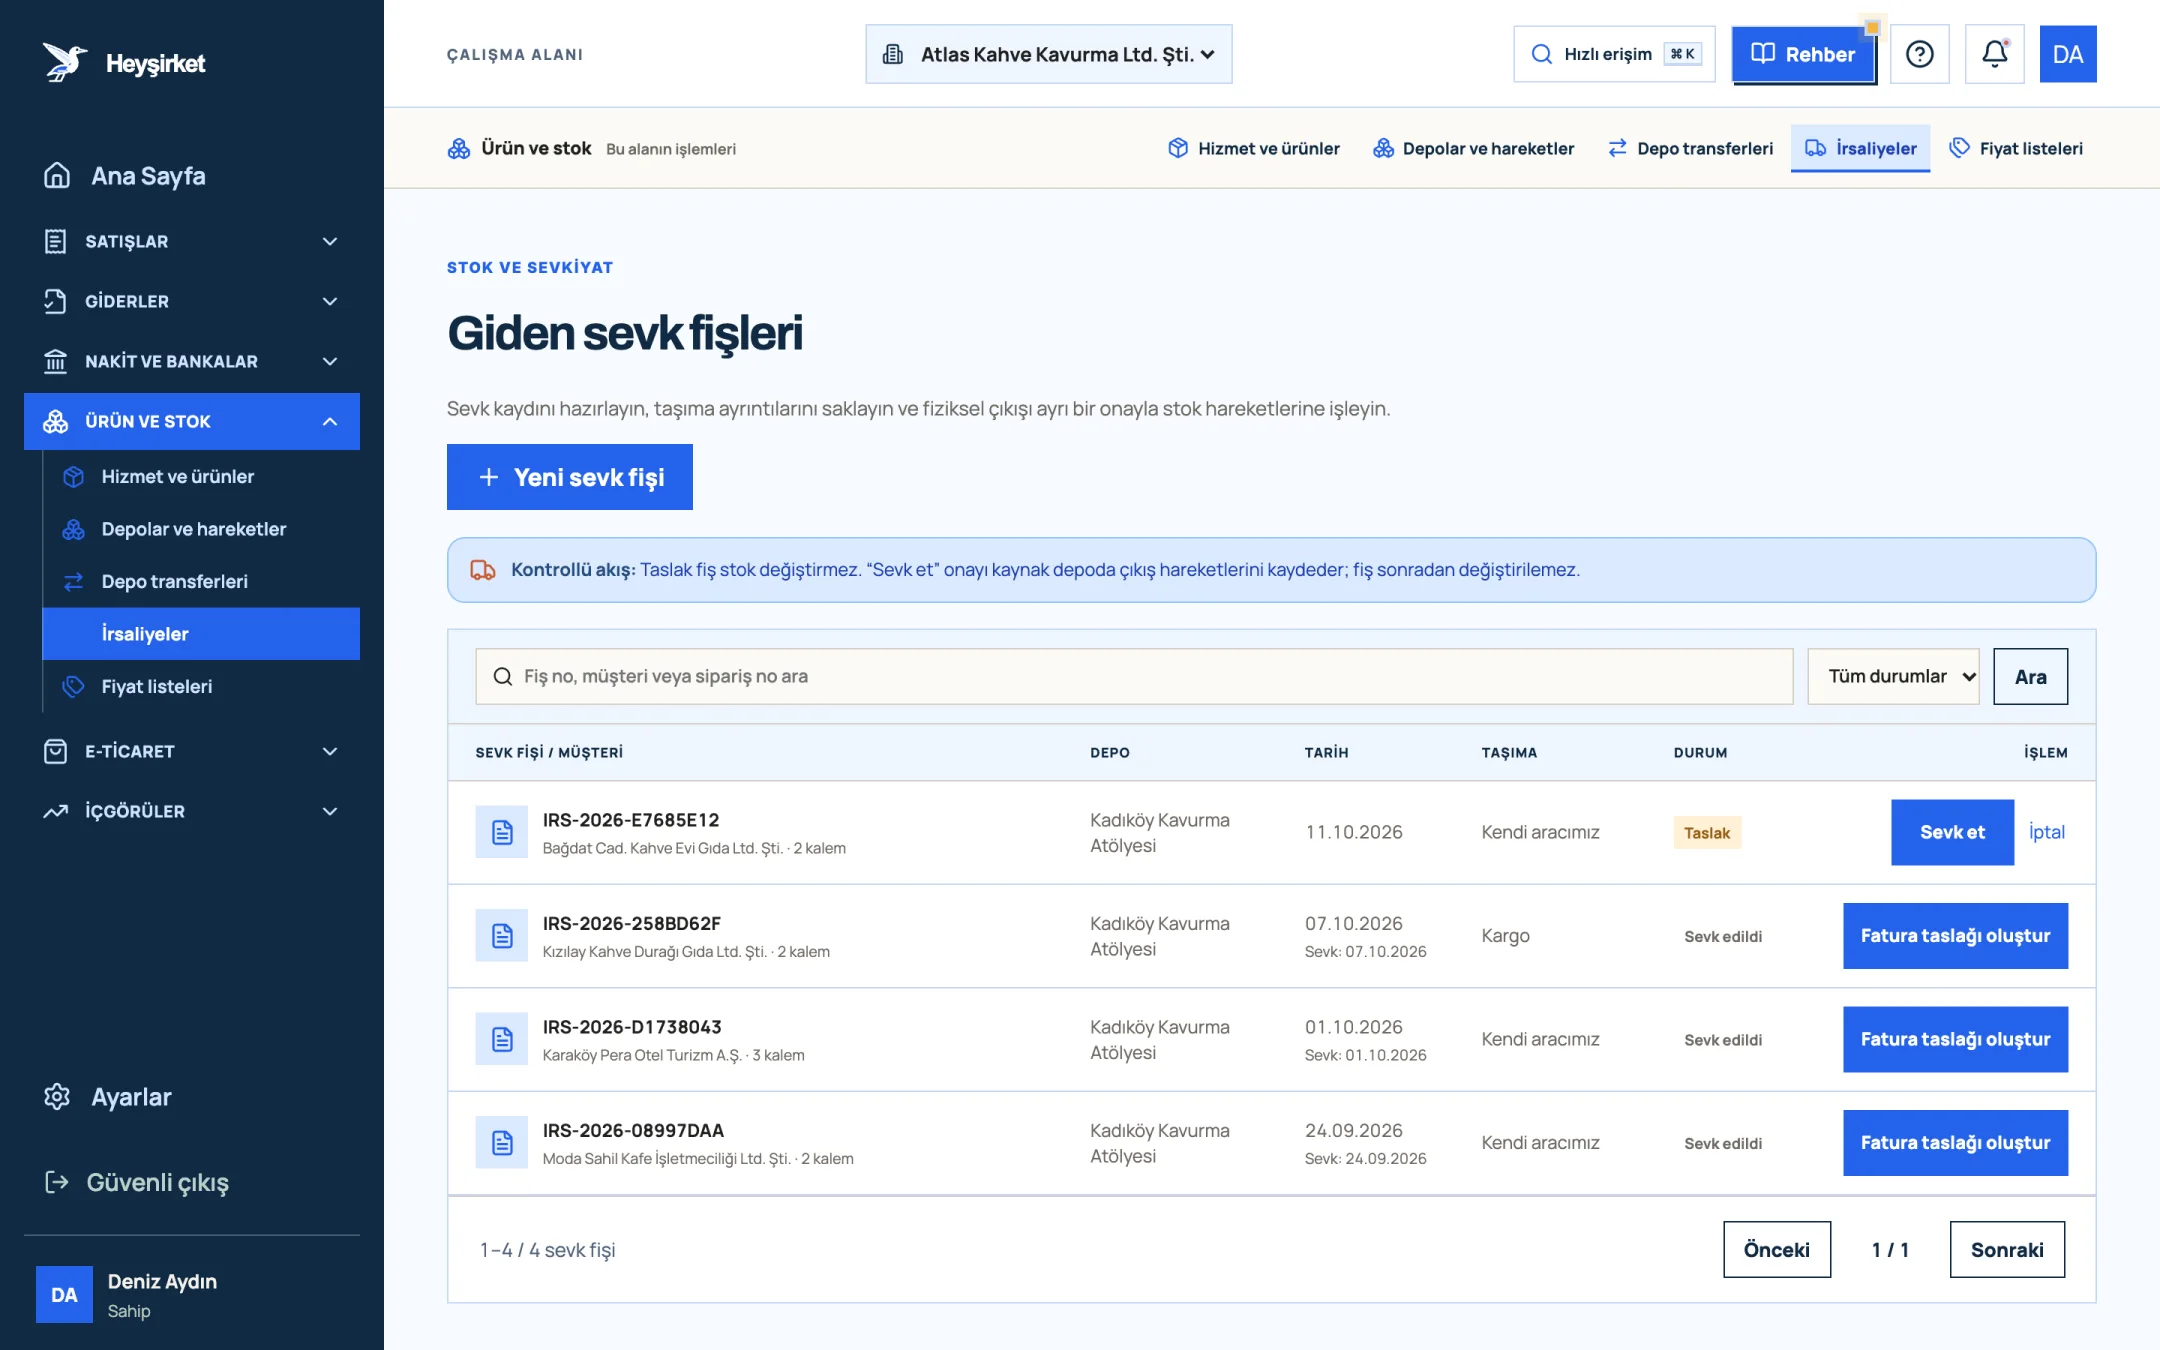
- 1. New delivery note
- 2. Shipping a draft note
- 3. Invoice draft from a shipped note
- 4. Controlled flow info
On the new invoice screen you can pick a past date in the Issue date field, and that date is passed to the official document as is. That helps for invoices issued a few days after delivery, but it doesn't make a date beyond the 7-day limit acceptable. The dispatch note flow is in how to prepare a dispatch note, and the invoice screen in how to issue an invoice.
Deadline and threshold checklist
- I record the date of every delivery or service.
- I issue invoices within 7 days of delivery at the latest.
- I invoice merchant and professional customers regardless of amount.
- I invoice consumer sales above 12,000 TL and whenever an invoice is requested.
- For partial deliveries I watch the deadline of the oldest dispatch note.
- I've agreed invoice timing for advances and ongoing services with my mali müşavir.
Within how many days must an invoice be issued?
An invoice must be issued within 7 days of delivering the goods or performing the service at the latest. An invoice not issued within that period is treated as never issued, and a special irregularity penalty may apply.
What is the 2026 invoicing threshold?
The 2026 invoicing threshold is 12,000 TL, effective from 1 January 2026 under VUK General Communiqué No. 588. Consumer sales above this amount must be invoiced.
Do I have to issue an invoice for sales under 12,000 TL?
If the buyer is a merchant, self-employed professional, farmer or tradesperson, an invoice is issued whatever the amount. If the buyer is a consumer, a retail receipt or cash register receipt is enough for sales of 12,000 TL or less, but you must issue an invoice if the buyer asks for one.
What is the penalty for not issuing an invoice in 2026?
Under VUK 353, a special irregularity penalty of 10% of the amount that should have been invoiced applies. In 2026 it can't be less than 17,000 TL for the first finding; the minimum rises to 35,000, 53,000, 70,000, 87,000 and 170,000 TL for later findings.
Are the invoicing threshold and the e-Arşiv threshold the same thing?
No. The invoicing threshold decides whether an invoice is mandatory. The e-Arşiv rule decides whether the invoice you issue must be electronic; from 2026, as a general rule, invoices are issued as e-Arşiv invoices whatever the amount.
Invoice what you ship, on time See your outgoing dispatch notes, create an invoice draft from dispatched ones in one click, and don't miss the 7-day deadline. Open dispatch notes
Author: Heyşirket Editorial Team